


Originally published September 26, 2025 | Updated September 2026
What is the Visa Acquirer Monitoring Program (VAMP) really?
The Visa Acquirer Monitoring Program (VAMP) is Visa’s framework for monitoring fraud and disputes across card-not-present transactions. It brings those signals together to help identify merchants and acquirers with unusually high levels of payment risk.
Think of it like a GPA. Instead of separate grades for math, English, and science, you get one score that determines if you graduate. In this case, graduation means keeping your ability to process Visa payments.
If you exceed the applicable thresholds, you could face assessments, remediation requirements, and increased scrutiny from your acquirer. Persistent problems can also put your merchant account relationship at risk.
VAMP raises the stakes for online businesses to keep fraud and customer disputes under control. Think of it like having a stricter referee watching every play: too many fouls can draw more scrutiny and require you to correct what’s going wrong.
For more information on what VAMP is, visit our glossary page. Or scroll down and keep reading to discover strategies for compliance!
The Story Behind Visa’s Move to Create VAMP
$40 billion saved—but fraud and chargeback cases are growing.
Visa says their fraud prevention programs saved over $40 billion last year. But as online transactions grow, so do bad actors. VAMP was designed to help acquirers strengthen their controls, prevent enumeration attacks, and reduce fraud across the global payments ecosystem. When Visa introduced VAMP, it said the program was designed to address four times the amount of fraud worldwide, representing more than $2.5 billion in losses.
The goal of this program can be broken down into three main points:
- Prevent enumeration attacks
- Reduce fraud globally
- Strengthen acquirer controls
Enumeration Attacks: A Real Example
Fraudsters can “guess” valid credit cards by testing thousands of small transactions—this is called an enumeration attack. Each successful hit is a risk for real fraud and chargeback issues. Visa flags these patterns early, helping businesses stop attacks before losses pile up and they hit the VAMP thresholds.
VAMP focuses on merchants, acquirers, and card-not-present transactions — essentially anyone selling online. If your processor notifies you that your business is under Visa’s monitoring program, it means your dispute and fraud levels are high enough to trigger an alert. Because excessive VAMP activity can trigger assessments and remediation requirements, acquirers have an incentive to act quickly. That can mean closer monitoring, required corrective action, or, in more serious cases, reconsidering the merchant relationship.
How the VAMP Ratio Works
The VAMP formula is straightforward: (TC40 fraud reports + TC15 disputes) ÷ settled transactions (TC05).

One important detail: because VAMP counts fraud reports and disputes separately, the same transaction can contribute both a TC40 fraud report and a TC15 dispute to your ratio.
Picture a subscription box company that charges a customer’s card. Months later, the card is reported stolen and the customer files both a TC40 fraud alert and a TC15 dispute. Both contribute to the VAMP count. If the business is already close to the applicable threshold, those two records could be enough to push its ratio over the limit and increase its VAMP risk.
The current VAMP threshold: As of April 1, 2026, the Excessive Merchant VAMP threshold is 1.5% in AP, Canada, the EU, the U.S. and LAC, with a minimum VAMP count of 1,500. Different criteria apply in CEMEA and certain other markets.
Check out more details via Visa’s VAMP fact sheet.
Pro tip: Set your own internal alert threshold below the VAMP limit that applies to your business. That gives you time to investigate rising fraud or disputes and take corrective action before you cross it.
Which Merchants Face the Most VAMP Risk?
Some industries naturally attract more fraud, such as:
- Crypto
- CBD
- Adult entertainment
- Gambling
Subscription businesses face unique challenges. Free trials that turn into forgotten charges, recurring billing that surprises customers, and so-called friendly fraud all increase the risk.
Proof in Practice: Subscription Surprises
An e-commerce business offers a $1 trial that automatically converts to $25 per month. When the first recurring charge hits, many customers forget they signed up or feel misled by unclear terms. This can trigger a spike in disputes, creating multiple TC15 and TC40 reports that push the VAMP ratio toward the threshold.
Proof in Practice: High-Risk Businesses Targeted by Stolen Cards
High-risk merchants, like CBD or adult entertainment sites, are more likely to be targeted by fraudsters using stolen credit cards. Later, when cardholders report the charges as fraud (TC40) and dispute them (TC15), both can count toward the VAMP ratio. That double impact can quickly push the business over its applicable threshold and increase its risk of assessments or remediation requirements.
In both the examples above, the business isn’t necessarily failing at fraud detection. Disputes can and often are caused by an individual merchant’s industry risk, product positioning, and/or unclear customer communication. High-risk merchants, in particular, may face closer monitoring from their acquirer, making it even more important to catch rising fraud and disputes early.
Why Non-Compliance With VAMP Requirements Hurts
Under this program, going over the limit means money out of your pocket.
Exceeding VAMP thresholds can trigger assessments and remediation requirements through your acquirer. Current processor guidance indicates an $8 assessment per dispute or fraud report for merchants that breach the Excessive VAMP threshold, although the costs ultimately passed on to a merchant may depend on their acquirer or processor agreement.
If fraud and disputes overlap, the same transaction counts twice.
Acquirers may also impose tougher rules of their own:
- Higher reserves
- Delayed payouts
- Stricter monitoring
In more serious cases, persistent compliance problems can put your merchant account at risk. Your acquirer may ultimately terminate the relationship, and terminated merchants that meet Visa’s listing criteria may also be reported to the Visa Merchant Screening Service (VMSS).
Still, exceeding VAMP thresholds doesn’t have to mean game over. If your VAMP ratio starts climbing, acting quickly to improve customer service, clarify billing descriptors, and strengthen fraud and dispute prevention can help bring it back under control.
VAMP Requirements and Compliance Made Simple
The key to surviving fraud and dispute monitoring programs isn’t reacting when fines hit. It’s about building proactive systems into your daily operations.
VAMP Compliance Checklist for Merchants
“Adopting a risk-based approach to fraud management allows organizations to allocate resources more effectively and respond swiftly to emerging threats.” Avivah Litan from Gartner, per the Merchant Fraud Journal
Use the checklist below to strengthen your approach to fraud and dispute management and reduce your risk under Visa’s Acquirer Monitoring Program:
- Monitor Your Ratio
- Set up a cadence to check it weekly, not monthly.
- Strengthen Fraud Prevention
- Implement stronger fraud controls, including identity verification and clear billing descriptors, to reduce avoidable fraud and disputes.
- Turn on 3D Secure, AVS, and velocity limits.
- Reduce Chargebacks
- Utilize prevention alert services like Verifi and Ethoca for pre-dispute intervention, and use Compelling Evidence 3.0 when eligible. Qualifying pre-dispute resolutions and CE3.0 fraud cases may be excluded from your VAMP calculation.
- Improve your Customer Service
- Overhaul your customer service — fantastic customer service sets you up for success as your customers call you instead of their bank. Do this by:
- Training customer support to resolve disputes fast
- Having a transparent cancellation process
- Sending reminders before charging subscription customers
- Overhaul your customer service — fantastic customer service sets you up for success as your customers call you instead of their bank. Do this by:
- Stay vigilant
- Treat this risk management checklist like a roadmap: monitor, act, adjust.
A business seeing a rise in TC40 fraud reports, for example, could strengthen 3D Secure, monitor affiliate traffic more closely, and use behavioral analytics to identify suspicious activity before it turns into a larger VAMP problem.
Think Beyond Fraud: Product Positioning, Offers, and Billing Plans
Fraud filters only solve part of the problem. Many chargebacks come from issues businesses can control, like hidden fees, disappointing products, or confusing billing plans. Fraud, on the other hand, often comes from affiliates driving low-quality traffic and even using stolen cards to earn commissions.
Businesses that manage risk under the Visa Acquirer Monitoring Program take a system-wide view.They monitor account health at every stage of the buying process — from traffic sources, to how offers are positioned, to subscription billing, to ongoing customer service.
For a deeper look at how these issues affect your ratios, thresholds, and overall account health, explore our guide to chargeback ratios and VAMP.
Clear vs. Confusing Subscription Offers

Imagine a subscription business with fraud tools that appear to be working well, but its disputes continue to rise. In that case, the fraud tools may be doing their job. The disputes could instead stem from unclear subscription terms, confusing billing descriptors, or charges customers weren’t expecting.
Reducing risk means looking at both sides: clearer positioning and billing can prevent avoidable disputes, while closer affiliate monitoring can help uncover fraud risks earlier. Together, these efforts create a full-lifecycle approach to protecting revenue and managing the fraud and disputes that contribute to your VAMP ratio.
Protecting revenue from avoidable disputes is one piece of a broader resilience strategy. Our guide to navigating an economic downturn explores additional ways businesses can protect cash flow, retention, and long-term growth.
What Happens When You’re Flagged Under VAMP
Being identified under VAMP doesn’t start one universal merchant countdown. What happens next depends on your VAMP status, applicable program criteria, and your relationship with your acquirer.
What to expect if you’re flagged:
- Notification and closer monitoring: Your acquirer will typically notify you of the VAMP issue and may increase scrutiny of your fraud and dispute activity.
- Remediation: You may need to identify the sources driving your VAMP ratio and take corrective action, such as strengthening fraud controls, addressing dispute drivers, or implementing additional remediation tools.
- Potential assessments: Depending on your VAMP status and acquirer or processor agreement, assessments may apply while your account exceeds the relevant program criteria.
- Exit from monitoring: Getting the applicable VAMP metrics back below the relevant program criteria is key to exiting monitoring. Your acquirer can confirm the specific requirements that apply to your account.
Mini-Case Study: Step-by-Step Remediation Plan
Flagged Under VAMP? Follow These Steps:
- Analyze the Problem: Identify transactions driving TC15 and TC40 reports.
- Adjust Product Positioning: Clarify trial terms, pricing, and billing descriptors.
- Strengthen Fraud Prevention: Activate 3D Secure, AVS, and velocity limits.
- Improve Customer Service: Train support to expedite dispute resolution and send reminders before recurring charges.
- Monitor Ratios Daily/Weekly: Track progress and adjust interventions as needed.
- Document Everything: Share your remediation steps with the acquirer to demonstrate proactive management.
✅ Result: Lower fraud and dispute activity, reduce your VAMP ratio, and work back toward the applicable program thresholds.
Prevention and proactive management are central to VAMP. The earlier you address rising fraud and disputes, the more room you have to reduce risk.
What’s Mastercard’s Equivalent to VAMP?
There isn’t a direct Mastercard version of VAMP. While Visa combines fraud reports and disputes within VAMP, Mastercard separately monitors excessive chargebacks through its Excessive Chargeback Program (ECP) and fraud through its Excessive Fraud Merchant (EFM) program.
How Mastercard’s Excessive Chargeback Program Works
Under Mastercard’s Excessive Chargeback Program, a merchant’s chargeback ratio is calculated using the current month’s chargebacks divided by the previous month’s Mastercard transactions. Merchants can then fall into one of two categories:
- Excessive Chargeback Merchant (ECM): 100–299 chargebacks and a chargeback ratio of 1.5%–2.99%.
- High Excessive Chargeback Merchant (HECM): 300 or more chargebacks and a chargeback ratio of 3% or higher.
Both the chargeback count and ratio must meet the applicable threshold for a merchant to fall into either category.
Mastercard separately monitors fraud through its Excessive Fraud Merchant (EFM) program. Rather than relying on the ECP chargeback thresholds alone, EFM considers factors including fraud-related chargebacks, transaction count, fraud ratio, and use of 3D Secure.
The takeaway for merchants is simple: Visa and Mastercard don’t measure payment risk the same way. Staying below your VAMP threshold doesn’t automatically mean you’re below Mastercard’s monitoring thresholds, so merchants accepting both card brands should monitor each program’s metrics separately.
Visa Acquirer Monitoring Program Timeline: What’s Changing and When
VAMP didn’t arrive all at once. Since its 2025 launch, Visa has rolled out the program in phases, with changes to thresholds and enforcement along the way. Understanding that history can help merchants make sense of the requirements in place today.
Important VAMP Enforcement Dates
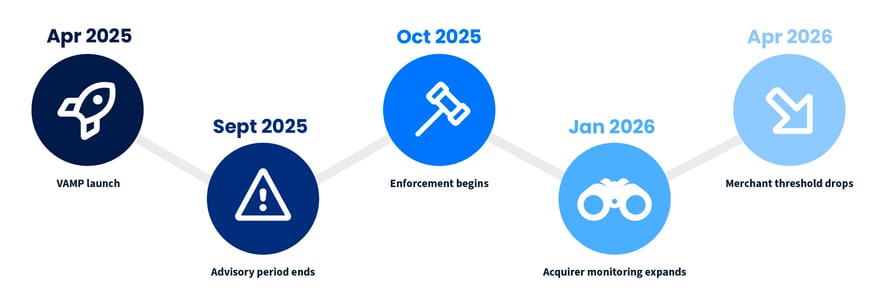
April 2025: New VAMP program launches.
September 2025: Advisory period ends.
October 2025: VAMP moves from the advisory period into enforcement, with assessments beginning October 1.
January 2026: Acquirer monitoring expands, with Visa introducing an Above Standard classification for VAMP ratios from 0.5% to less than 0.7%. Acquirers at 0.7% or higher remain classified as Excessive.
April 2026: The Excessive Merchant VAMP threshold drops from 2.2% to 1.5% across AP, Canada, the EU, and the U.S., bringing those regions in line with the 1.5% threshold already used in LAC. The minimum VAMP count is 1,500.
These dates aren’t just technical milestones — they show how VAMP has evolved into the program merchants and acquirers face today. With enforcement active and the current thresholds in place, the focus now is on monitoring fraud and disputes closely, catching problems early, and taking action before rising VAMP metrics lead to assessments or remediation requirements.
The Bottom Line on Visa’s VAMP Program
VAMP is strict, but manageable. Businesses that act early can reduce their compliance risk, protect revenue, and strengthen customer trust. The sooner you treat fraud and disputes as part of your entire business model, the better positioned you’ll be to keep your VAMP ratio under control.
That’s where Sticky.io CRM can help. Our subscription-first platform gives you the tools to manage offers, billing, payments, and customer retention in one place — helping you build a stronger customer experience while managing the issues that can contribute to VAMP risk.
Get in touch to get started today!
Calculate Your VAMP Ratio to See Your Risk of Impact
Knowing the formula is one thing, but seeing how it applies to your business is what really matters. An increase in fraud reports or disputes can quickly raise your VAMP ratio, especially when the same transaction contributes both a TC40 fraud report and a TC15 dispute.
Our free interactive calculator makes it easy to plug in your numbers and estimate your VAMP ratio based on your current fraud reports and disputes.
Use it to monitor your VAMP risk and spot changes in your fraud and dispute activity before they become a larger problem. Try it today to see where your ratio stands.
Prefer a full-page version? The same calculator lives in our calculator library.